
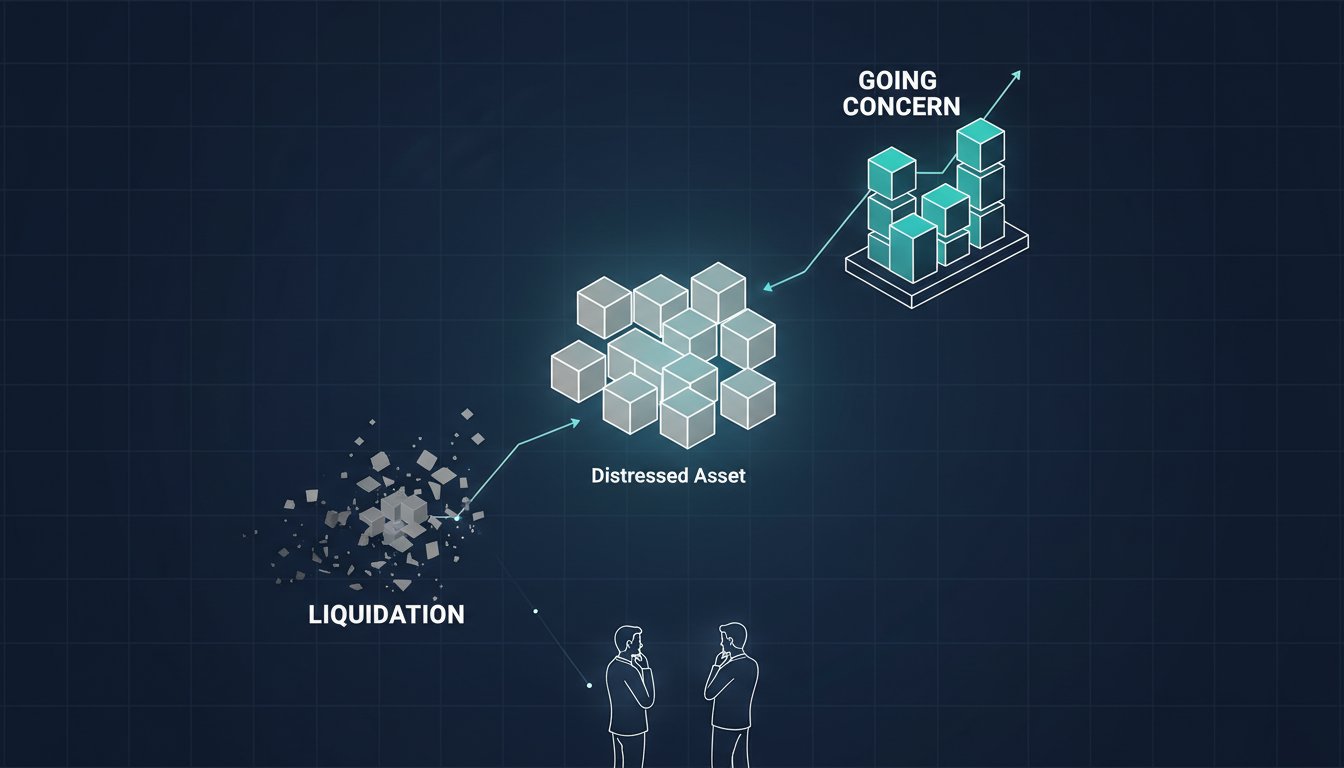
Standard valuation frameworks are rendered ineffective in the face of distressed scenarios. The complexities of negative cash flows, extreme forecast uncertainty, and the absence of reliable comparables demand a more sophisticated analytical approach. For institutional investors, the ability to accurately value distressed assets is not merely an analytical exercise-it is a critical determinant of portfolio performance in high-stakes environments where the margin for error is nonexistent.
This methodological guide provides the definitive framework for institutional-grade analysis. We deconstruct the core methodologies required, from adapting Discounted Cash Flow models for turnaround scenarios to executing precise liquidation valuations. The objective is to equip your team with a robust, data-driven process to identify key value drivers, mitigate inherent risks, and make defensible investment decisions with precision and confidence.
Foundational Framework: Choosing the Correct Valuation Premise
The process to accurately value distressed assets begins with a single, critical decision: is the underlying business a going concern? This initial determination, a core tenet in the Valuation of a suffering company, dictates the entire methodological framework and ultimate financial outcome. The choice hinges on a data-driven assessment of the probability of a successful turnaround versus an asset sell-off. This framework establishes two primary valuation premises that guide all subsequent analysis.
To visualize the nature of these assets, consider the following overview:
The Going-Concern Premise
The going-concern premise assumes the company will continue operations, potentially after a significant financial or operational restructuring. This approach is appropriate when a viable core business exists, and the distress is primarily financial rather than existential. The valuation focuses on projecting future earning power and cash flow generation. Methodologies like the Discounted Cash Flow (DCF) analysis are central to this premise, as they quantify the present value of the enterprise's expected future performance.
The Liquidation Premise
Conversely, the liquidation premise is engaged when a business is deemed non-viable or is worth more disassembled than operational. Under this scenario, the company is expected to cease operations and sell its assets. Value is derived from the net proceeds generated by selling these assets individually or in discrete packages, after satisfying all liabilities. This approach requires rigorous, detailed asset appraisals and a comprehensive assessment of secured and unsecured claims to determine the residual value available to stakeholders.
Orderly vs. Forced Liquidation
Within the liquidation premise, a further distinction is critical. The chosen scenario directly impacts recovery values and must be selected based on market conditions and creditor demands.
- Orderly Liquidation: Involves selling assets over a reasonable time period, allowing for proper marketing and negotiation to maximize sale proceeds. This method typically yields higher values.
- Forced Liquidation: Implies an accelerated sale process, often conducted via auction under duress. This scenario is common in bankruptcy proceedings and typically results in significant discounts to market value due to compressed timelines.
The applicable scenario is dictated by factors such as creditor pressure, cash burn rate, and court-mandated deadlines.
Valuing as a Going Concern: Adapting Traditional Models for Distress
When you value distressed assets, standard valuation models predicated on stable growth and predictable cash flows are inadequate. The core challenge shifts from forecasting expansion to modeling survival and turnaround probabilities. In this high-stakes environment, valuation is less an academic exercise and more a strategic assessment of a credible restructuring path. The focus must be on adapting proven frameworks, such as DCF and relative valuation, to account for extreme operational and financial uncertainty.
Modified Discounted Cash Flow (DCF) Analysis
A DCF for a distressed firm cannot rely on historical performance. Instead, projections must be anchored to a meticulously detailed and defensible restructuring plan. The analysis requires several critical adjustments to accurately reflect the heightened risk profile:
- Scenario Modeling: Develop multiple, probability-weighted scenarios. These typically include a successful turnaround, a stagnation or "muddle-through" case, and a liquidation scenario.
- Elevated Discount Rate: The Weighted Average Cost of Capital (WACC) must be significantly higher to incorporate the acute risk of bankruptcy and operational failure.
- Adjusted Terminal Value: The terminal value calculation should be conservative, often incorporating a probability of failure that reduces or eliminates its contribution to the total valuation.
Relative Valuation (Comparable Company Analysis)
Identifying truly comparable distressed companies is a significant analytical hurdle. Financial metrics are often skewed by non-recurring charges, negative earnings, and unsustainable capital structures. To overcome this, investors must use alternative metrics and data sources. A review of established distressed asset valuation techniques confirms the need for this adaptability. Key adjustments include using revenue-based multiples like EV/Sales when EBITDA is negative and analyzing precedent M&A transactions involving companies that have successfully emerged from restructuring. All comparisons must be heavily adjusted for differences in leverage and operational health.
Estimating the Cost of Capital for Distressed Firms
Calculating the WACC for a distressed entity requires a departure from standard inputs. The firm's existing capital structure is often unsustainable and its market data is volatile, rendering conventional calculations misleading. A robust approach to value distressed assets involves building the cost of capital from the ground up.
- Adjusted Beta: A company's equity beta is often inflated by high leverage. It should be unlevered and then re-levered based on a target, post-restructuring capital structure.
- Cost of Debt: Use the current yield-to-maturity on the company’s traded debt, which directly reflects its present default risk, rather than its coupon rate.
- Distress Premium: Many analysts add an explicit distress premium (e.g., 3-10%) to the cost of capital to quantitatively account for the unique risks not captured in beta or the cost of debt alone.
The Liquidation Approach: A Sum-of-the-Parts Valuation
When a corporate turnaround is unfeasible, the investment thesis shifts from operational recovery to asset monetization. The liquidation approach is a systematic, data-driven methodology designed to value distressed assets based on their individual sale potential. This sum-of-the-parts analysis disregards going-concern assumptions and instead focuses on the orderly disposal of tangible and intangible holdings. The primary objective is to establish a defensible "floor value"-the minimum recoverable capital from the portfolio. The precision of this valuation is directly correlated with the accuracy of recovery estimates for each distinct asset class.
Step 1: Asset Identification and Appraisal
The foundational step is a meticulous inventory and appraisal of all company assets. This is not a simple balance sheet review but a granular assessment of market-based value. Key actions include:
- Tangible Asset Appraisal: Commission independent appraisals for real estate, machinery, and equipment to determine their Orderly Liquidation Value (OLV).
- Current Asset Analysis: Scrutinize accounts receivable for collectability, applying a significant discount based on age and customer quality. Inventory is valued at its likely recovery rate, which may be a fraction of its book value.
- Intangible Asset Valuation: Identify and value intangible assets like patents, trademarks, or customer lists, but only if they are separable and can be sold to a third party.
Step 2: Liability Analysis and Payout Waterfall
Once gross asset value is estimated, the focus shifts to the claims against those assets. This requires identifying all outstanding liabilities and structuring them according to absolute priority. This hierarchy, detailed in any comprehensive distressed investing guide, dictates the order of payment from asset sale proceeds. The typical "payout waterfall" prioritizes claims as follows: secured debt, administrative expenses, priority unsecured claims, general unsecured claims, and finally, equity interests. The value to any stakeholder is the residual claim they hold after all senior tranches are satisfied.
Step 3: Calculating Net Liquidation Value (NLV)
The final calculation refines the gross asset value into a net figure available for distribution. To determine the Net Liquidation Value (NLV), you must subtract all anticipated costs associated with the wind-down and asset sale process. These deductions typically include legal fees, trustee fees, auctioneer commissions, and other administrative costs of bankruptcy. Further discounts may be applied to asset values to account for transaction friction and the accelerated timeline of a liquidation. The resulting NLV represents the total capital pool to be distributed to claimants according to the payout waterfall, providing a clear framework to value distressed assets for stakeholders at every level of the capital structure.
Special Considerations: Valuing Debt and Navigating Bankruptcy
In distressed scenarios, the investment focus often shifts from equity to debt, where the debt instrument itself becomes the traded asset. The valuation process transcends standard financial modeling, entering a complex domain governed by legal frameworks. To accurately value distressed assets, institutional investors must integrate rigorous financial analysis with a deep understanding of bankruptcy proceedings, creditor rights, and recovery hierarchies.
This synthesis of financial and legal expertise is non-negotiable for capitalizing on opportunities within distressed markets. The outcome of a restructuring or liquidation is dictated as much by court rulings and creditor negotiations as it is by the company's underlying enterprise value.
Valuing Distressed Debt
The intrinsic value of distressed debt is the present value of its expected recovery. This calculation is a function of several critical inputs. An analyst must determine the "recovery value" based on a meticulously forecasted enterprise value post-restructuring or the liquidation value of its assets. This recovery is then allocated according to the absolute priority rule, making the debt's seniority in the capital structure paramount. Finally, the timeline to resolution must be factored in, as protracted legal proceedings can significantly erode returns.
Impact of the Italian Legal Framework
Jurisdiction-specific regulations create unique challenges and opportunities. In Italy, insolvency proceedings such as concordato preventivo (composition with creditors) introduce structured, court-supervised processes that heavily influence timelines and outcomes. The dynamics within creditor committees and the court's role in approving restructuring plans or asset sales are critical variables in the valuation model. Navigating these complexities requires specialized expertise. Access curated Italian distressed assets on our platform.
The Role of Covenants and Collateral
A granular analysis of loan agreements is essential to the due diligence process. Key elements to scrutinize include:
- Covenants: Financial and operational covenants can act as early warning signals or default triggers, providing creditors with leverage long before a formal bankruptcy filing.
- Collateral: For secured debt, the quality and liquidation value of the pledged assets are of utmost importance. This collateral provides a valuation floor, establishing a baseline for recovery prospects and mitigating downside risk.
This detailed assessment of legal rights and security packages is a cornerstone of any credible strategy to value distressed assets and is fundamental to constructing a robust investment thesis.
From Theory to Practice: Leveraging Technology in Distressed Asset Analysis
Successfully executing a distressed asset strategy requires more than sound financial theory; it demands a significant informational advantage. The process to value distressed assets is inherently complex, involving fragmented data, tight deadlines, and high stakes. In this environment, institutional investors who leverage advanced technology can accelerate due diligence, mitigate risk, and move from analysis to execution with superior confidence and speed.
Modern platforms provide a critical edge by transforming the entire valuation workflow. Access to reliable data, efficient analytical tools, and secure communication channels is no longer a luxury-it is the core of a competitive advantage.
AI-Powered Preliminary Due Diligence
Proprietary algorithms can screen enormous volumes of portfolio data in minutes, not weeks. This AI-powered intelligence automatically extracts critical financial KPIs, identifies covenant breaches, and flags outliers that require deeper investigation. By delivering instant ROI projections based on preliminary data, these systems empower investment teams to discard unviable assets and focus capital and resources exclusively on the most promising opportunities.
Secure Virtual Data Rooms (VDRs)
Distressed transactions depend on the secure exchange of highly sensitive financial, legal, and operational documents. A certified Virtual Data Room (VDR) is essential for maintaining control and confidentiality. Key features include:
- Granular Access Controls: Ensure stakeholders see only the information relevant to their role.
- Advanced Security: Protect intellectual property with dynamic watermarking, disabled printing, and end-to-end encryption.
- Compliance and Audit Trails: Track all document activity to provide a complete, defensible record of the due diligence process.
Building a Defensible Valuation with a Data-Driven Edge
Ultimately, technology enables the fusion of methodological rigor with powerful analytics. A centralized, intelligent platform ensures all valuation models are built upon a single source of verified data, eliminating discrepancies and streamlining communication between legal, financial, and operational teams. This integrated approach creates a robust, data-driven framework to value distressed assets accurately and build a defensible investment thesis. Join the SIMI network to access our intelligent ecosystem.
From Methodology to Marketplace Advantage
Mastering the methodologies to accurately value distressed assets is a critical capability for institutional investors navigating complex markets. As we have explored, success hinges on a disciplined selection of the correct valuation premise-be it going concern or liquidation-and the rigorous adaptation of financial models to unique risk profiles. While this analytical framework is the foundation, superior execution is where alpha is ultimately generated and captured.
Transitioning from theory to high-value portfolio action demands a technologically sophisticated and secure platform. The SimInvest intelligent ecosystem is engineered precisely for this purpose. Gain a decisive advantage with our AI-Powered Intelligence and comprehensive due diligence materials, all secured within a Virtual Data Room featuring end-to-end encryption. Put this guide's principles into practice with exclusive access to curated Italian private market assets. Explore verified Italian distressed credit opportunities on the SIMINVEST marketplace and empower your investment strategy with the market's leading engine.
Frequently Asked Questions
What is the primary difference between valuing a healthy company and a distressed one?
Valuation of a healthy company focuses on its going-concern value, typically derived from predictable future earnings and cash flows using methods like DCF or comparable company analysis. In contrast, distressed valuation often pivots to asset-based approaches. The central question becomes whether the entity is worth more as a restructured going concern or through an orderly liquidation of its assets. This requires a dual-track analysis that healthy company valuations do not.
How does the absolute priority rule in bankruptcy affect the valuation of different claims?
The absolute priority rule (APR) establishes a strict pecking order for claim repayment during bankruptcy proceedings. Secured creditors are paid first from their collateral, followed by unsecured creditors, and lastly, equity holders. This waterfall structure is critical for valuation, as the enterprise value determines which tranches of the capital structure are "in the money." A junior debt claim may be valued at zero if senior claims exceed the company's total determined value.
What are the most common mistakes analysts make when valuing distressed assets?
A primary error is over-optimism regarding a management turnaround plan, leading to unrealistic cash flow projections. Another frequent mistake is misjudging the true market value of assets in a forced or orderly liquidation scenario. Analysts who fail to accurately model the complex capital structure and the timeline of bankruptcy proceedings will fundamentally miscalculate recoveries. To properly value distressed assets, one must avoid these biases and focus on data-driven recovery analysis.
How can you value a company with negative EBITDA and cash flow?
When traditional metrics like EBITDA are negative, valuation shifts to alternative methodologies. An asset-based approach, determining the Orderly Liquidation Value (OLV) of assets, provides a valuation floor. Alternatively, a Discounted Cash Flow (DCF) analysis can be used if a credible turnaround plan exists, projecting a path back to positive cash flow. This requires applying a significantly higher discount rate to account for the elevated execution risk and uncertainty.
What role does management's turnaround plan play in a going-concern valuation?
The turnaround plan is the central pillar of a going-concern valuation for a distressed entity. It provides the financial projections-revenue growth, cost reductions, and capital expenditures-that form the basis of a DCF model. However, these projections demand rigorous scrutiny. An analyst must stress-test all assumptions, assess execution risk, and evaluate management's track record. A non-credible plan forces the valuation back toward a liquidation analysis, as the going-concern premium is unjustified.
Is it possible to use option pricing models (like Black-Scholes) for distressed valuation?
Yes, option pricing theory provides a sophisticated framework to value distressed assets, particularly equity. The equity of a highly leveraged firm can be modeled as a call option on the company's assets, with the face value of debt serving as the strike price. This approach is effective for quantifying value in situations of high uncertainty and volatility, where the binary outcome of recovery or wipeout resembles an option's payoff structure.